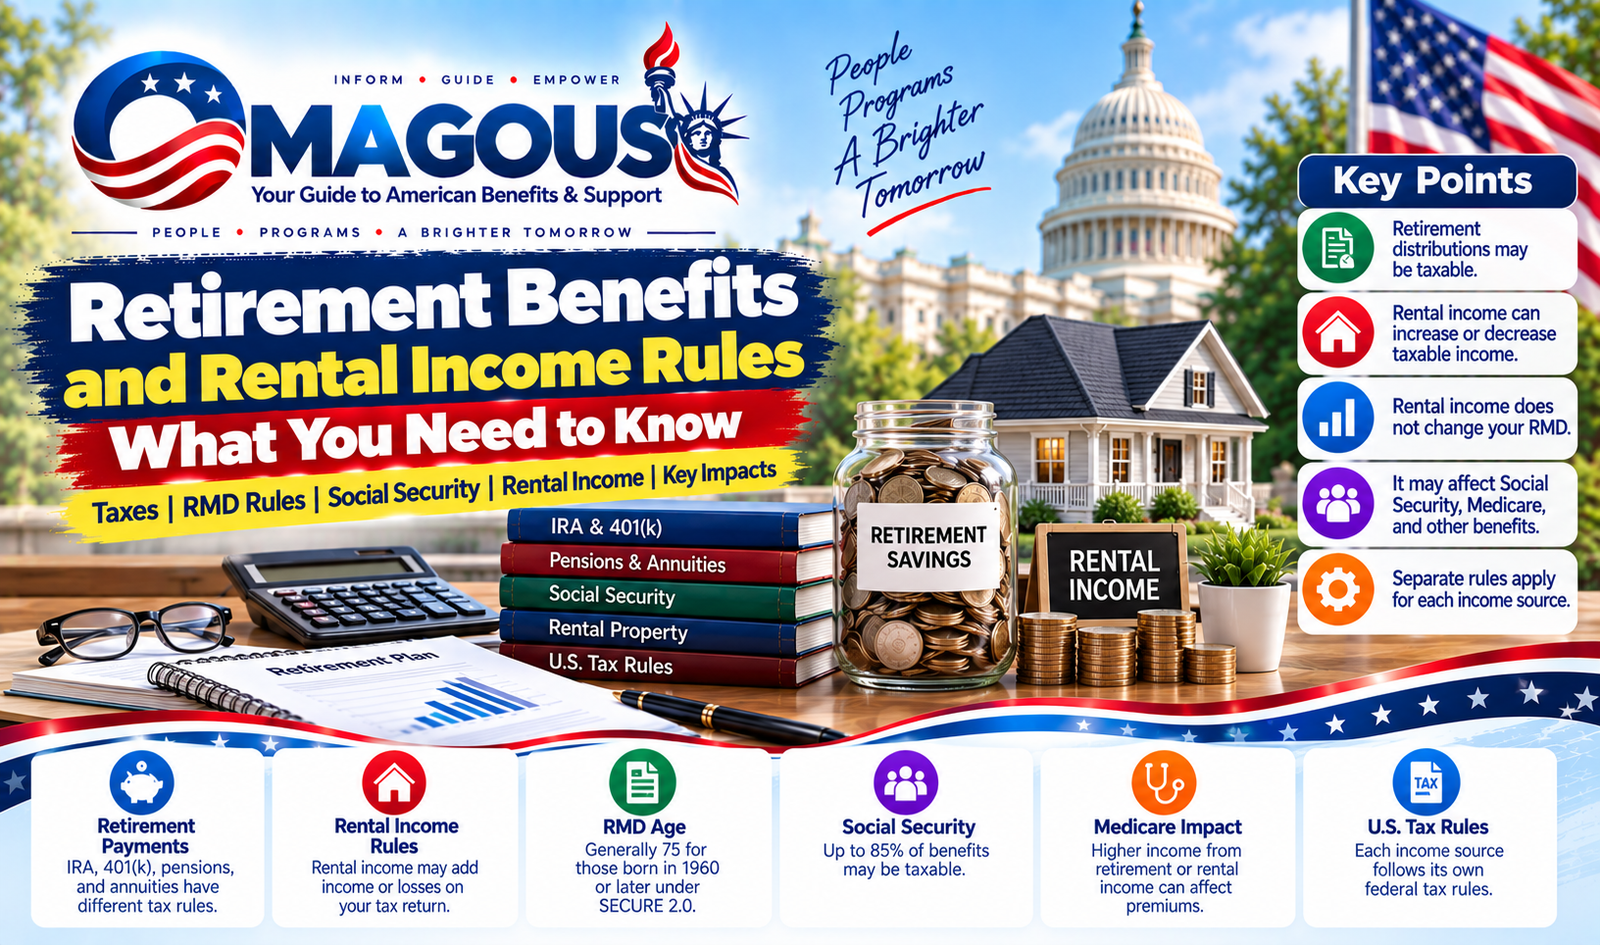
Retirement Benefits and Rental Income Rules can feel like two separate tax systems, but your return may connect them. A pension or individual retirement arrangement can supply the cash you live on, while rent can raise or lower taxable income. The real risk is treating one payment rule as if it applies to the other.
Under SECURE 2.0, the required minimum distribution age is generally 75 for someone born in 1960 or later, with older cohorts following 73, 74, or 75. Rental income usually doesn’t change that RMD calculation, even when it raises taxable income. Start with the quick answer, then sort each payment by source, ownership, and purpose.
Retirement Benefits and Rental Income Rules
Quick Answer
Retirement Benefits and Rental Income Rules govern separate U.S. tax calculations. Retirement distributions may create taxable income. Rental property may add income or losses.
Rental income doesn’t change an IRA or employer-plan RMD. It can still affect taxes, conversions, Social Security, Medicare, and means-tested benefits.
Retirement Benefits: Which Payments Are Taxable?
Most retirement payments are taxable at least partly, but the account and payment type control the result. An individual retirement arrangement, or IRA, is only one part of retirement income. Pensions, annuities, and Social Security benefits follow different rules.
How common retirement payments are treated
| Income source | General federal tax treatment |
|---|---|
| Traditional IRA, SEP IRA, or SIMPLE IRA | Pretax contributions and earnings are generally taxable. After-tax basis may be recovered tax-free. |
| Roth IRA | Qualified distributions are generally tax-free. Early distributions can still trigger an exception-based penalty. |
| 401(k) or 403(b) | Pretax amounts are generally taxable. Qualified designated Roth distributions are generally tax-free. |
| 457(b) plan | Governmental and tax-exempt plans have special penalty and rollover rules. A lump sum can create added tax complexity. |
| Defined benefit pension | Payments are generally taxable after any allocable basis is recovered. |
| Private annuity | Payments are generally taxable to the extent they exceed your investment in the contract. |
| Social Security | Up to 85% of benefits may be taxable under the standard federal rules. |
| Railroad retirement | Tier 1 benefits receive Social Security-like treatment. Tier 2 benefits are generally taxable. |
Roth IRA rules require a five-year period and an age requirement for qualified earnings distributions. Meeting one condition alone doesn’t complete the requirement. Exceptions can apply to disaster distributions, certain first-home purchases, and other situations listed in the IRS rules.
Nonqualified deferred compensation is generally taxable when received, although some compensation may be taxable before payment if required by the applicable deferred-compensation rules. State tax treatment can differ from federal treatment.
The IRS retirement plan guidance is the best starting point for current plan rules. The official Social Security Administration provides benefit calculations and annual cost-of-living adjustments.
What is taxable inside a retirement distribution?
Your distribution may contain a tax-free return of after-tax contributions. Pretax earnings remain taxable, and a partial distribution can mix basis with earnings. Account statements and the plan’s year-end tax breakdown matter more than the account’s current balance.
Correcting an incorrect Social Security record can change the monthly benefit and its taxable amount. Correcting age records is an important first step when a date of birth is wrong. If the issue involves missing wages, benefit recomputation guidance explains the review process.
Survivor benefits can also change your retirement income mix. Comparing survivor options before a spouse dies can prevent an avoidable benefit reduction. Our discussion of survivor income choices covers that decision more closely.
Do rental activities change the RMD?
No. The starting age is generally 73 for someone born during 1950 through 1952, 74 for 1953 through 1955, and 75 for 1956 or later. SECURE 2.0 provides future increases above 75, beginning after 2029.
An eligible employment exception can delay an RMD under some employer plans. That exception doesn’t delay required distributions from an IRA. Rental income also doesn’t change the account balance used to calculate the annual distribution.
A missing Form 1099-R does not eliminate a required distribution. The owner should contact the plan administrator for a corrected tax statement. Roth IRA owners have no lifetime RMD, but their heirs may face distribution deadlines after the owner dies.
Rental Income: What Must You Report?
Rental receipts generally belong on your federal return whether you receive a Form 1099 or not. A tenant’s failure to issue one doesn’t remove your reporting duty.
What counts as rental income?
| Receipt | General treatment |
|---|---|
| Residential or commercial rent | Usually reported as gross rental income. |
| Room and board | Often includes both rental and meals. The IRS provides a simplified method for certain cases. |
| Land, parking, or storage rent | Report the amount received or made available for use. |
| Mobile-home lot rent | Generally treated as rental income. |
| Short-term rental receipts | Gross receipts are reported first on Form Schedule C when the activity is a business. |
| Prepaid rent | Generally included in income during the year received. |
| Security deposit | Usually not income when received. Treatment changes if it represents rent or you retain it for tenant-caused damage. |
Image source: Wikimedia Commons / JianfaTsai
Most individual landlords report long-term rental income and expenses on Schedule E. Short-term rentals with substantial services can qualify as a business. For that business, you generally report gross receipts on Schedule C, then deduct expenses and pay applicable self-employment tax.
A state of ten rentals doesn’t automatically establish a business. The IRS looks at the type of services, control, customization, and other facts. A long-term tenant who receives a finished home with minimal landlord involvement will usually be treated differently from a business serving transient guests.
How should unusual payments be handled?
Noncash rent generally has a fair market value. That can apply to property, services, or barter arrangements. Get a defensible valuation before the exchange, especially if the arrangement involves a related person.
If you rent to a family member below market rent, part of the arrangement may be treated as a gift. You also lose the ability to claim losses that exceed income from the rental. If rent is above market, maintain records showing how the amount was determined.
Cash rent requires the same reporting as electronic rent. Keep the lease, payment history, bank deposits, and any written expense reimbursement policy. A written policy helps separate a refundable deposit from a final rent payment.
Security deposits require careful treatment. A returned deposit normally isn’t income. A payment for unpaid rent can be taxable.
Amounts kept for actual damage generally aren’t income, but they may reduce the landlord’s repair deduction.
Most rental taxpayers report income when payment is received or constructively received. An accrual method may apply when that method is permitted and the return consistently uses it.
If rental income also replaces Supplemental Security Income, housing arrangements and countable income become separate concerns. Our explanation of family housing guidance shows why a normal tax lease may not match the program’s payment rules.
How Rental Income Affects Retirement and Benefit Calculations
Rental income enters some retirement-related calculations, but it doesn’t alter the retirement account itself. You need to test each program separately.
Which calculations can rental income affect?
| Calculation | Treatment of rental activity |
|---|---|
| Federal income tax | Net rental income generally increases taxable income. Claimable rental deductions may reduce it. |
| IRA or employer-plan RMD | Rental income and rental losses normally don’t change the RMD. |
| Roth conversion | Net rental income can increase modified adjusted gross income and taxable conversion income. |
| Social Security taxation | Rental income can increase provisional income, making more benefits taxable. |
| Medicare premiums | Rental income can affect Additional Medicare Tax and income-related premium rules. |
| SSI or Medicaid | Program counting rules and lookback periods may differ from tax-return rules. |
Modified adjusted gross income, or MAGI, is the starting point for several retirement and benefit calculations. It generally starts with taxable income before certain deductions.
Roth conversion income includes the conversion amount, even if the IRA was tax-free. A $20,000 conversion can therefore add $20,000 to MAGI. Rental losses generally don’t reduce that figure when they are suspended passive losses.
A rental real estate trade or business may qualify to use a net operating loss. That can change the result, because a net operating loss may offset more than passive income. The activity’s facts and reporting method need review before taking that position.
Why rental income matters for Social Security
Social Security taxation is based on provisional income. That figure is built from adjusted gross income, tax-exempt income, and the taxable portion of Social Security benefits. Rental cash flow can push more benefits into the taxable range.
For example, suppose you receive $24,000 in rent and deduct $9,000 of expenses. Suppose you also claim $4,000 of depreciation. Your reported net rental income would generally be $11,000, assuming all those deductions are allowed.
That $11,000 may increase the taxable portion of your Social Security benefits. It doesn’t reduce the benefit amount itself. Any tax due from the return is separate from the Social Security Administration’s benefit calculation.
A suspended passive loss usually won’t lower provisional income. An allowed net operating loss may. Don’t assume the amount shown on Schedule E automatically reduces every retirement-related income test.
How rental income can affect Medicare costs
The Additional Medicare Tax is generally 0.9% of the taxpayer’s net investment income above set thresholds. Rental income can be investment income. Traditional retirement distributions, Roth conversions, and Social Security can also contribute to the calculation.
The Medicare Savings Program uses separate income limits and counting rules. Rental records needed for taxes may not match the records requested by the program. Eligibility can also depend on household circumstances, so low income prescription help is worth checking before costs rise.
Income-related Medicare premiums use a different test. The Medicare program generally uses a two-year lookback and can apply Part B and Part D premiums of up to 35%. A large rental gain can raise MAGI, but the result may not appear until later.
If you receive SSI or Medicaid, a profitable rental activity may affect countable income and resource rules. The single-person SSI threshold changes with household circumstances and benefit rules. Check those rules rather than using the tax calculation as a shortcut.
Personal Ownership or Retirement Account Ownership?
Personal ownership is usually simpler for cash access, but a rental inside a tax-exempt retirement account creates major tax and legal concerns. Neither structure is automatically better.
What changes with the ownership structure?
| Structure | Current rent | Main tax issue |
|---|---|---|
| Personal ownership | Available to the owner | Reported under the relevant rental activity rules. |
| IRA ownership | Normally unavailable for personal use | Rental activity may create unrelated business taxable income. |
| Partnership or LLC | Usually available under entity rules | Passes income, losses, and deductions through to owners. |
| Estate or trust | Depends on its terms | Has its own income, deduction, and beneficiary rules. |
Personal ownership usually gives you straightforward access to rent. You report income, claim eligible expenses, and deal with investment or trade or business classification. Rental losses remain subject to the passive activity rules.
An LLC doesn’t automatically make rental activity a business or a loss deductible against salary. A single-member LLC is generally disregarded for federal tax purposes. A partnership passes rental results to owners through Form 1041 and Schedule K-1.
What happens when rental property is inside an IRA?
An IRA can hold real estate if the custodian accepts the asset and the transaction follows applicable rules. Rental activity conducted through the IRA may create unrelated business taxable income, or UBTI. UBTI is income from a trade or business unrelated to the account’s tax-exempt purpose.
A profitable rental inside an IRA generally doesn’t create current ordinary rental income for the owner. That doesn’t make the rent tax-free. It also doesn’t prevent deductions from creating or reducing UBTI, which makes the treatment more complex.
The owner generally can’t take rent, occupy the property, or use it for personal business. Those actions can be prohibited transactions involving the IRA. Renting to a family member or receiving a favorable tenant arrangement can also create self-dealing concerns.
Directly transferring personally owned rental property to an IRA can be a prohibited transaction. Appreciated property may also create a separate UBTI problem. Get written advice from a tax attorney or qualified professional before changing ownership.
As of 2026, annual IRA contribution limits still apply to contributions used to acquire an asset. The asset must be valued correctly on the required date. Announced limits don’t create unlimited purchasing power through a self-directed IRA.
What to check before buying through an IRA
Find an IRA custodian that accepts real estate before closing. Confirm how it handles deposits, property management, insurance, repairs, and distributions. Some custodians only accept a narrow range of investments.
Use an independent property manager when appropriate. The account should pay ordinary and necessary expenses directly. Any owner benefit, reimbursement, or family arrangement needs careful review before the lease begins.
An IRA can face financing, insurance, title, and management challenges that a personal owner may not. Don’t choose the structure for tax savings alone. A property that can’t be insured, maintained, or lawfully used may become worse for you than taxable rent.
Rental Deductions, Depreciation, and Loss Treatment
Only expenses that are ordinary, necessary, and connected with producing rental income are deductible. Your records should show what you paid, when you paid it, and how it relates to the property. Keep personal spending in a separate account.
Which rental costs are deductible?
| Cost | General treatment |
|---|---|
| Mortgage interest | Deductible when allocable to the rental and documented. |
| Property tax and insurance | Usually deductible for the rental period. |
| Utilities | Deductible when separately metered or fairly allocated. |
| Repairs and maintenance | Deductible when they maintain the property in condition. |
| Depreciation | Potentially deductible for qualifying depreciable property. |
| Personal expenses | Not deductible, including commuting and household costs. |
Mortgage principal isn’t deductible, but mortgage interest may be. Home improvements aren’t deductible simply because cash leaves your account. Qualifying improvements may be depreciated instead.
Repairs preserve the property’s condition. Replacing the roof, adding a bathroom, or upgrading a building may be a capital improvement. Track each project from the start so you can separate costs correctly.
How is depreciation calculated?
Depreciation begins when the property is placed in service, not when you buy it. Most residential rental real estate is depreciated over 27.5 years under the Modified Accelerated Cost Recovery System, or MACRS. Nonresidential property is generally over 39 years, while Alternative Depreciation System lives are often 30 and 40 years.
Qualifying improvements may receive a 15-year life.
Suppose a property costs $400,000 and $80,000 of that amount is allocated to land. The depreciable basis starts at $320,000, plus qualifying closing costs and improvements. A mid-month convention can affect the first-year deduction, so use the applicable tax tables or software.
When can you deduct vacation-home expenses?
A vacation-home deduction generally requires a genuine rental-profit motive. You also need to track rental days and personal-use days. Personal use normally cannot exceed 50% of the property’s total use during the relevant period.
Rent for 14 days or fewer still creates income. The safe harbor blocks deductions unless you charge at least fair market rent and support the arrangement. Renting a room in your primary residence can qualify under a separate exclusive-rental arrangement.
Can a rental loss reduce other income?
Only in limited situations. A passive loss can offset passive rental income, but not salary, pension, or IRA withdrawals. A suspended loss normally carries forward to future passive activity.
The rental professional exception may allow broader loss treatment when the ownership, participation, income, and time tests are met. Those tests include at least $100,000 in gross rents and 500 hours of qualifying participation during the year. Net operating loss rules may also change the result, so classify the activity before allocating a loss across your return.
Step-by-Step Decision and Tax-Reporting Workflow
Use this order to keep retirement income, rental activity, and benefit calculations separate until the final return.
Create a payment inventory. Include pensions, IRAs, employer plans, Social Security, rent, deposits, reimbursements, and entity payments. Include cash and electronic transfers.
Classify every retirement item. Record the gross distribution, taxable amount, basis code, and rollover status. Check whether the payer issued Form 1099-R and whether an exception applies.
Separate retirement basis from earnings. Subtract eligible after-tax contributions before treating a distribution as fully taxable. Pension or IRA withdrawals don’t change because rent was received or lost.
Classify the rental activity. Decide whether it is passive, a trade or business, partnership activity, or IRA-owned rental activity. Property labels and entity names don’t determine the classification.
Total gross rental receipts. Record cash rent, prepaid rent, room and board, storage fees, and tenant reimbursements. A missing Form 1099 doesn’t remove the reporting requirement.
Sort and allocate costs. Separate deductible expenses from personal and capital costs. Allocate shared utilities, insurance, and mortgage interest between rental and personal use.
Calculate the rental result. Track adjusted basis, land value, accumulated depreciation, and suspended losses. Then calculate net income, passive loss, or net operating loss.
Choose the correct reporting method. Long-term passive rental activity is usually reported on Schedule E. Business activity generally uses Schedule C, while partnership or LLC owners receive a Schedule K-1.
Reconcile the return. Compare your figures with Forms 1099-R, SSA-1099, 1098, and K-1. Box 1 on Form 1099-R shows the total distribution, while Box 2 shows the reported taxable amount.
Estimate tax and preserve records. Use prior returns, expected deductions, credits, and withholding to estimate payments. Keep account notices, leases, ledgers, receipts, mileage records, invoices, and depreciation workpapers.
For example, suppose you withdraw $50,000 from a traditional IRA and recover $20,000 of after-tax basis. Your taxable retirement distribution is $30,000. If rental receipts equal $12,000 and allowed deductions total $7,000, the rental result adds $5,000.
The two amounts combine on your return, but the rental result doesn’t reduce the IRA RMD.
Common Mistakes That Can Cause Financial Trouble
Most expensive mistakes come from applying one rule to accounts or properties that only look similar. Use this review before filing or correcting a return.
| Common mistake | Better approach |
|---|---|
| Using one RMD age for everyone | Check the birth year, applicable plan rules, and SECURE 2.0 changes. |
| Treating every retirement withdrawal as taxable | Identify after-tax basis and any tax-free amounts first. |
| Applying one five-year rule to 401(k), 403(b), and 457(b) plans | Review each plan’s own service and separately owned plan rules. |
| Offsetting passive rental losses against pension income | Apply passive loss rules or document a valid exception. |
| Renting a home for 14 days and claiming deductions | Report the rent and test the fair-market-rent condition. |
| Reporting every short-term rental as passive | Review substantial services, business indicators, and self-employment tax. |
| Assuming an LLC makes the activity a business | Apply federal tax classification rules to the actual owner and facts. |
| Transferring rental property into an IRA casually | Review prohibited transactions, valuation, and UBTI first. |
| Calling every property expense a repair | Separate maintenance, restoration, improvement, and land costs. |
| Ignoring rent when no 1099 arrives | Report the income and retain leases, deposits, and bank records. |
Correct ownership and income classification first. A wrong reporting choice can distort deductions, loss carryforwards, and tax payments across several years. Don’t rush into an amended return for a minor difference.
First compare the additional tax, interest, and any accuracy-related penalty with the expected recovery.
The IRS generally requires a taxpayer to file a separate Form 1040-X to correct a return. Its treatment of a substantial omission or erroneous deduction can differ from a simple mathematical correction. A preparer can identify which error caused the problem and which form is appropriate.
Legal, Compliance, and Professional-Help Warnings
Rental tax compliance is only one layer of the rules. State, local, housing, employment, and insurance law can apply at the same time.
Federal tax law doesn’t control every state retirement or rental tax. Some states exempt pension income, while others tax retirement withdrawals differently. They may also treat rental income, capital gains, or deductions on a different basis.
Federal fair housing law restricts discrimination during advertising, tenant selection, rental terms, and enforcement. State and local rules can add tenant protections, lease requirements, security deposit deadlines, and habitability standards. A landlord also needs insurance that covers the actual property use.
Short-term rentals may require registration, permits, occupancy taxes, zoning approval, inspections, and platform data collection. Hosting agreements don’t override local law. Vacation-rental policies can also change during the year, so verify local requirements before accepting a reservation.
Property condition creates risks beyond the tax return. A title defect, flood exposure, environmental problem, or unsafe repair may produce a large loss. An LLC only helps when it has genuine risk protection.
Personal guarantees, negligent conduct, and state veil-piercing rules can still expose the owner.
When should you bring in a professional?
Bring in qualified help before filing if the transaction involves an IRA-owned property, cross-border ownership, or a complex entity.
| Professional | Useful for |
|---|---|
| CPA or enrolled agent | Rental returns, depreciation, entity returns, and payroll taxes |
| Tax attorney | IRA transactions, cross-border issues, complex entities, and disputed positions |
| Plan administrator | RMDs, rollovers, loans, and plan-specific distribution rules |
| Local landlord attorney | Leases, tenant disputes, permits, and fair housing compliance |
| Property manager | Tenant screening, maintenance, rent collection, and local operations |
| Insurance or title professional | Coverage gaps, title defects, flood risk, and ownership changes |
Nonresident aliens and U.S. expatriates may face separate filing and reporting duties. U.S. rental income can also create exposure to nonresident capital gains rules and estate tax. A cross-border specialist should review the facts before you buy, transfer, or refinance the property.
Before closing, confirm the permitted use, current tax treatment, insurance availability, and repair responsibility. Write those answers into the closing checklist. A deal that looks attractive only because of a tax deduction deserves a second professional review.
Frequently Asked Questions
Does rental income change my RMD?
No. Rental income and net rental losses normally don’t change the account value used to calculate an IRA or employer-plan RMD. They can change federal taxable income, Social Security taxation, Medicare premiums, or means-tested benefits.
The plan’s permitted lifetime distribution method is a separate calculation.
Can rental losses reduce pension or IRA income?
Only in limited situations. A passive loss can offset passive rental income, but not ordinary salary, pension, or IRA distributions. The rental professional exception or net operating loss treatment may allow broader offsets if every test is met.
Can I deduct expenses for a vacation home?
Generally, yes, but only when the property qualifies. For a vacation home, you generally need a genuine rental-profit motive. The 14-day rule can block deductions, and personal use above 50% during the relevant period usually prevents a rental loss.
Is short-term rental income self-employment income?
Sometimes. Long-term rental activity is commonly passive. Short-term activity with substantial services can be a business, requiring gross receipts on Schedule C and possible self-employment tax.
Local permits, occupancy taxes, zoning, and insurance rules may also apply.
How do I report rental income without a 1099?
Yes, report the income even when the tenant fails to send a 1099 or pays in cash. Keep the lease, payment records, bank deposits, expense receipts, and property-use calendar. Compare the amount with your ledger before filing.
Can I own rental property in an IRA?
It is possible, but high-risk. The IRA custodian must accept real estate, and the account may face unrelated business taxable income. Personal use, prohibited transactions, self-dealing, valuation, insurance, and management issues can make this unsuitable without professional advice.
Pingback: Retirement Benefit Reductions Before Full Retirement Age - OMAGOUS